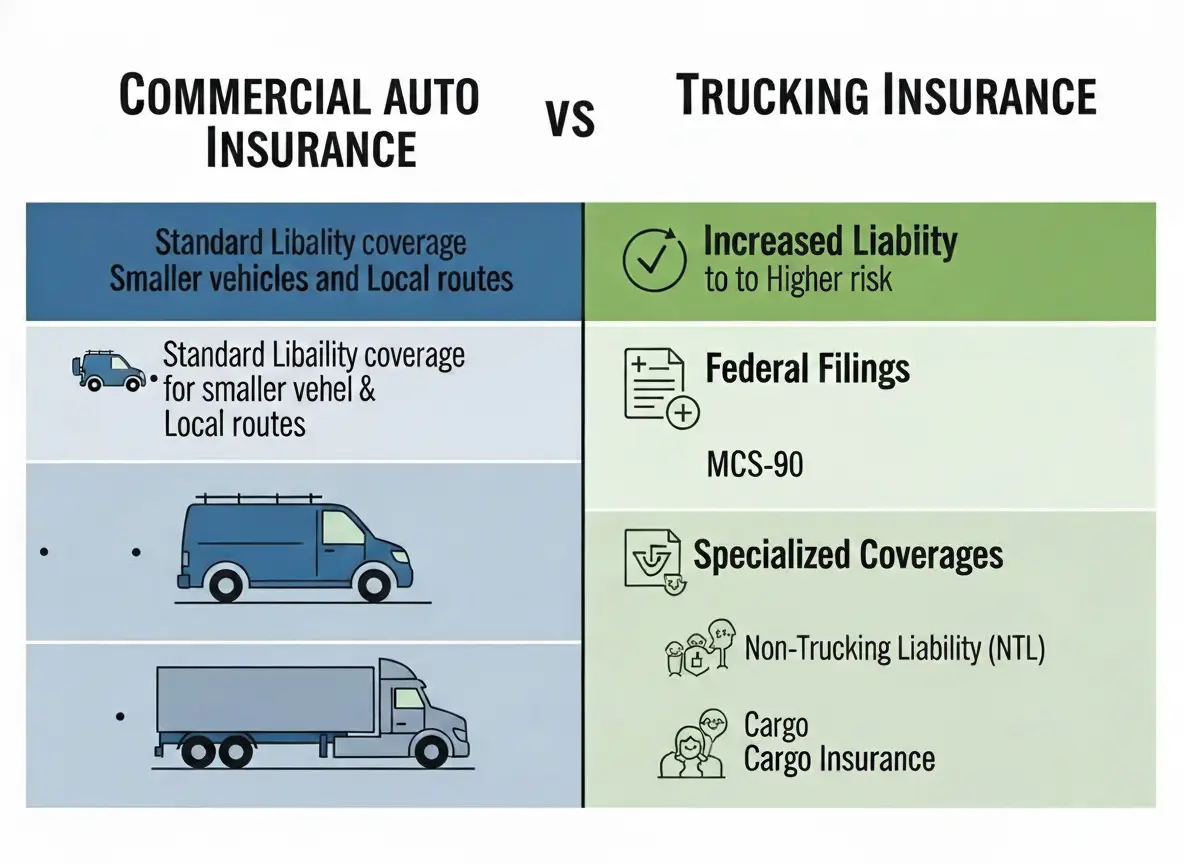
Commercial auto insurance covers vehicles a business uses, like a contractor's pickup or a delivery van. Trucking insurance is commercial auto written for motor carriers that haul freight for hire: it includes the liability limits and federal or state filings your authority needs, plus coverages such as motor truck cargo, non-trucking liability and trailer interchange. If you haul other people's goods for pay, you almost always need a trucking policy.
What does commercial auto insurance cover?
A commercial auto policy covers liability and, if you choose it, physical damage for vehicles your business owns or uses. It fits businesses where the vehicle supports the work rather than being the work: plumbers, electricians, landscapers, caterers and sales teams. The insurer prices it around local driving, light vehicles and business errands.
What makes trucking insurance different?
Trucking insurance starts from the same building blocks (liability and physical damage) but is designed for carriers whose business is moving freight. The main differences:
- Filings: interstate for-hire carriers must have their insurer file proof of liability coverage with FMCSA (a BMC-91 or BMC-91X) before the authority becomes active, and the policy carries the MCS-90 endorsement. Many states have their own filings for intrastate carriers.
- Higher liability limits: federal minimums for most for-hire freight trucks rated at 10,001 lbs or more start at $750,000 under 49 CFR 387.9, and many brokers and shippers ask for $1,000,000.
- Cargo coverage: motor truck cargo covers the customer's freight, which a normal commercial auto policy doesn't.
- Trucking-only coverages: non-trucking liability (often called bobtail) for leased owner-operators, trailer interchange, reefer breakdown and similar endorsements.
- Underwriting: insurers look at CDL experience, radius, commodities, CSA data and loss runs in ways a general commercial auto program doesn't.
When is commercial auto enough?
Commercial auto is usually the right fit when you carry your own tools, materials or products and nobody pays you to haul freight. A landscaping company with a dump trailer or a business with a cargo van for its own deliveries is typically here. Weight, distance and whether you cross state lines can still trigger DOT registration, so check the rules for your vehicle.
When do I need trucking insurance instead?
You need a trucking policy when you:
- have, or are applying for, your own MC authority to haul regulated freight for hire;
- pull loads from brokers or shippers who require a certificate showing auto liability and cargo;
- run a hotshot, box truck or semi for hire, even with a single truck;
- are an owner-operator leased to a carrier and need non-trucking liability or physical damage on your own unit.
If you're not sure which side you are on, our article on what insurance a trucking company needs walks through each coverage, and the FMCSA liability minimums explains the federal floor.
What goes wrong when the wrong policy is used?
The most common problem is a claim on a load the policy was never meant to cover. A personal or general commercial auto policy may exclude for-hire hauling, cargo isn't covered at all, and without the right filing FMCSA can't activate or keep your authority. Brokers check certificates, so the gap often shows up as lost loads before it shows up as a denied claim.
What should I tell my agent to get the right policy?
- Whether you haul your own goods or other people's for pay.
- Your USDOT and MC numbers, or that you are applying for them.
- The vehicle (year, make, GVWR) and any trailers.
- What you haul, how far, and in which states.
- Who drives and their experience.
With those answers, an agent can tell you whether you belong on a commercial auto or a trucking program and quote the coverages that apply. See the full list on our Coverages page.
Frequently asked questions
Is trucking insurance a type of commercial auto insurance?
Yes. Trucking insurance is commercial auto coverage written for motor carriers, usually by insurers or programs that specialize in transportation. The difference is in the extras: federal or state filings, cargo, non-trucking liability, trailer coverage and underwriting built around for-hire hauling.
Can I use a regular commercial auto policy to haul freight for hire?
Only if the policy is written for that use. Many commercial auto policies exclude or don't contemplate hauling other people's goods for hire, and the insurer must be able to make the federal or state filing your authority needs. Tell the agent exactly what you haul and for whom.
Does a box truck need trucking insurance or commercial auto?
It depends on how it is used. A box truck hauling freight for hire under its own authority usually needs a trucking policy with filings and cargo coverage. A box truck that only carries the owner's own goods, such as a contractor's tools, is often written on a commercial auto policy.
Which is cheaper, commercial auto or trucking insurance?
They cover different risks, so the price comparison isn't useful on its own. A policy that is cheaper because it doesn't fit your operation may not respond to a claim or satisfy FMCSA and your brokers.
Sources
- 49 CFR 387.9 – Financial responsibility, minimum levels (eCFR) – accessed Nov 7, 2026
Coverage depends on the policy terms; this is general information, not advice.
Want a quote for your operation?
Tell us about your trucks, drivers, lanes and cargo. GuildRoad Insurance Agency shops trucking markets and explains the options in plain language.
Start my quote